Extra mortgage payments could save you thousands in interest, but is it always the right call? Weigh up the pros, cons and rules before you overpay.
Overview
This guide evaluates the financial viability of early mortgage repayment in Ireland, weighing the benefits of interest savings against the importance of liquidity and alternative investments.
Mechanics of Overpayment
- Methods: Borrowers can make lump sum payments from windfalls or set up regular monthly overpayments.
- Impact: Extra payments can be used to either reduce monthly installments (increasing immediate disposable income) or shorten the mortgage term (maximising long-term interest savings).
Strategic Decision Factors
To ensure an overpayment is the most efficient use of capital, borrowers should consider the following:
- Cost of Debt: Prioritise clearing high-interest debt (credit cards/personal loans) before low-cost mortgage debt.
- Emergency Liquidity: Maintain a "rainy day fund" of six months' net income to avoid being "asset rich but cash poor."
- Lender Penalties: Fixed-rate contracts may incur Early Repayment Charges (ERCs), though many Irish lenders permit fee-free overpayments of up to 10% per annum.
- Opportunity Cost: Capital may yield higher returns if directed toward pensions (due to 40% tax relief) or high-yield investments rather than debt reduction.
- The "Switching" Alternative: If overpaying is not viable, switching to a lower interest rate can reduce costs without depleting cash reserves.
Introduction
Paying off your mortgage early might seem like a no-brainer to most people. When you take out a mortgage to buy a home, it is likely to be the largest financial commitment you will ever make. The thought of finally clearing that debt and being entirely mortgage-free is a dream for many.
However, there are a few important things to consider before you start to throw money at your bank. Whether you have built up excess savings, received a big bonus at work, inherited some money, or simply managed your monthly budget well, you might find yourself in the lucky position to knock a chunk off your mortgage or overpay by a set amount each month.
But is paying off your mortgage early in Ireland always the smartest financial move? While reducing your debt is generally positive, the decision depends heavily on your interest rate, your existing savings, and whether you might face an early repayment charge.
This guide will walk you through exactly what a mortgage overpayment is, the benefits of clearing your mortgage debt ahead of schedule, and the key financial factors you need to weigh up before making a final decision.
What is a mortgage overpayment?
A mortgage overpayment is simply when you pay more towards your mortgage balance than your required monthly payment. You can usually do this in two different ways depending on what suits your budget and your long-term financial goals.
The first method is making a lump sum payment. This is a one-off payment made directly against your outstanding mortgage balance. It is a popular option if you receive an unexpected windfall, such as an inheritance, a work bonus, or the maturity of a savings scheme.
The second method is making regular overpayments. This involves increasing your monthly repayments by a set amount. For instance, if your normal monthly payment is €1,200, you might choose to pay €1,300 instead. Over time, these additional payments add up significantly and slowly chip away at the total amount you owe.
Before you consider either route, it is highly recommended to use a mortgage overpayment calculator. A reliable mortgage overpayment calculator will help you clearly see how different overpayment amounts will impact your overall term and the total interest you pay.
The benefits of paying off your mortgage early
Overpaying on your mortgage is usually a good idea because it means you will potentially save tens of thousands of euro in interest and be mortgage-free much quicker.
Because interest is calculated on your outstanding mortgage balance, every euro you overpay reduces the principal amount. This means you are charged less interest in the following months and years.
For example, if you have €200,000 left on your mortgage over a 15-year term and are paying an interest rate of 3.50%, you would save around €5,700 in interest over the remaining term if you paid just €20,000 off the capital.
Being mortgage-free also provides immense psychological benefits. Knowing that you own your home outright brings a level of financial security and peace of mind that is hard to match. It completely frees up your monthly income, allowing you to redirect those funds towards other financial goals, such as saving for retirement, helping your children with education costs, or simply enjoying a more comfortable lifestyle.
How to make a mortgage overpayment
If you decide to overpay on your mortgage, an important thing to consider is exactly how your lender will apply the overpayment. When you make extra payments, you generally have two main options to choose from:
- Keep your mortgage term the same but reduce your monthly repayments: In this scenario, the extra money you pay reduces your overall mortgage balance, and your bank recalculates your future payments over the existing timeline. This will give you more disposable income each month, but it will not help you pay off your home any faster.
- Keep your mortgage repayments the same and make a lump sum payment off the capital balance: This will actively reduce the term of your mortgage and mean you are mortgage-free quicker. This option is usually recommended by financial experts as you will pay far less interest overall.
Seven things to consider before paying off your mortgage early
While it can feel great to clear your debt, financially it does not always make sense. Here are seven crucial questions to ask yourself before making a mortgage overpayment.
1. Do you have a rainy day fund?
Most experts advise that you have a rainy day fund that is equivalent to around six months of your net disposable income.
So if you take home €3,000 a month after tax, ideally you should have around €18,000 in an easy-access savings account for emergencies. You never know when you might face unexpected medical bills, a sudden job loss, or urgent home repairs. If you do not have an adequate amount of savings, you should strongly consider building up your cash reserves before you look at paying extra off your mortgage.
2. Will you need to borrow in the near future?
Your mortgage will likely be the lowest cost form of debt that you have. That is because, unlike other loans, it is secured lending. Your home is used as security against your mortgage, and technically the bank can take back your home and sell it if you do not make repayments over a long period of time.
Most people will be paying between 2.50% and 5% interest on their mortgage. This compares to personal loan rates of around 8% to 10% and credit card rates of up to 20% or more. There is no point paying a chunk off your mortgage if you are going to have to borrow at a much higher rate for some home improvements or a new car a few years later.
3. Do you have existing debt?
If you have other more expensive debt, then you should pay this off first.
There is no point paying €25,000 off your mortgage which is charging you 3% interest if you also have a €25,000 car loan that is charging you 10% interest. If you have extra money, you should always look at paying off your most expensive debt first. Because mortgage rates are generally lower than personal loans and credit cards, your home loan is unlikely to be your most expensive debt.
4. Will you be penalised?
If you are on a fixed rate and pay off your mortgage early, or even just overpay, you may be charged a fee. The charge will depend heavily on your specific lender and the number of years you have remaining on your fixed-rate contract.
However, some lenders now allow you to overpay up to 10% of the outstanding balance on your mortgage each year without incurring a fee. And if you are on a variable rate, there is usually no issue with overpaying whatsoever. Either way, always check carefully with your lender about any potential early repayment charge before you overpay so that you make the right decision.
5. What is your savings rate?
If you have money saved or invested somewhere that is making a good return, it might be better to keep your money exactly where it is.
For example, if your savings are making a return of 7% or 8% a year, and the interest rate on your mortgage is only 2% or 3%, it would not make financial sense to use your savings to pay off your mortgage. You are earning more on your money than you are saving on interest, so keeping your cash in the high-yield account is the smarter move.
6. Think about liquidity
We have all heard of the expression “asset rich but cash poor”.
It might be great to live in a home that is worth half a million euro and be almost entirely mortgage-free, but if you have got no money for emergencies, holidays, or unexpected health expenses, then you could still find yourself in trouble financially.
Some people can be far too aggressive in trying to pay off their debt, and it can end up backfiring. So consider how much easy access to money you think you will need in the short to medium term before locking all your spare cash into your property.
7. Do you have adequate pension provision?
We are all living much longer, and most of us can expect to spend around 20 years in retirement, if not more. But how do you plan to pay for your golden years?
Most people's pension pots are nowhere near large enough to fund the type of lifestyle they want in retirement. So you should consider whether it is better to pay into your pension and allow your money to grow tax-free over the coming years.
Most people's pensions will be invested in funds that should grow between 4% and 6% a year, if not more. This is likely to be far higher than the interest you are paying on your mortgage. Furthermore, if you are a top-rate taxpayer, you can also get 40% tax relief on any pension contributions you make up to a certain limit.
Conclusion
Psychologically, it can feel brilliant to be free of debt. But as outlined above, whether to pay a lump sum off your mortgage will ultimately come down to your individual circumstances. What is right for one person may not be right for the other. Make sure you get good financial advice before making a decision so that you do what is best for your specific situation.
If overpaying is not the right choice for you right now, another highly effective way to pay less interest on your mortgage is to switch to a better rate. Switching may not be an option for absolutely everyone, and there are some small costs involved, but you could significantly reduce your monthly repayments and not even have to touch your hard-earned savings.
If you are thinking of switching your mortgage, check out our free mortgage broker service on bonkers.ie today. Our dedicated team of experienced financial advisors here in Dublin will help you with your entire switch from start to finish, ensuring you get the very best value available on the market.
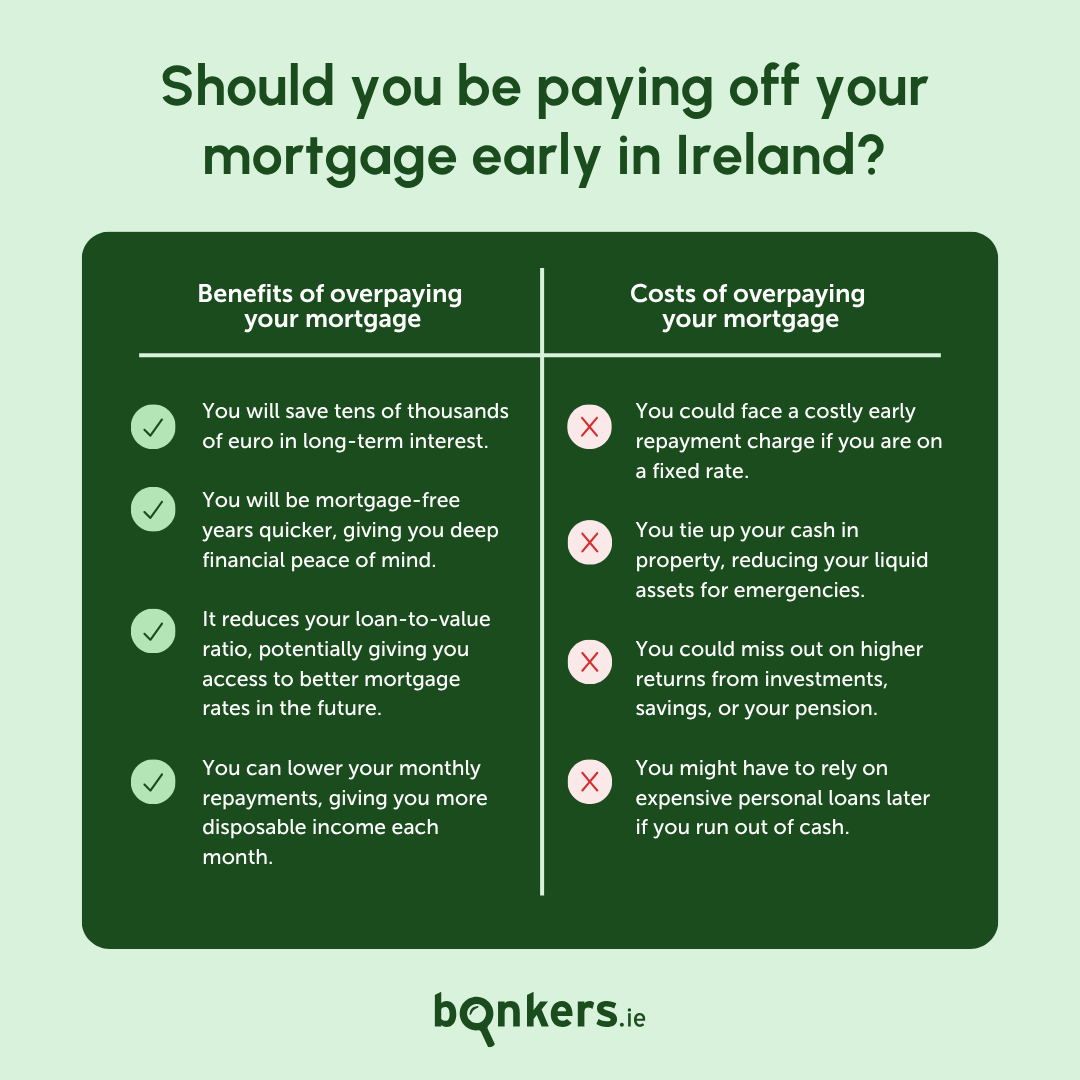
Summary table: Pros and cons of paying off your mortgage early
To help you weigh up your options, here is a quick summary of the main advantages and disadvantages of a mortgage overpayment.
|
Pros of overpaying your mortgage |
Cons of overpaying your mortgage |
|
You will save tens of thousands of euro in long-term interest. |
You could face a costly early repayment charge if you are on a fixed rate. |
|
You will be mortgage-free years quicker, giving you deep financial peace of mind. |
You tie up your cash in property, reducing your liquid assets for emergencies. |
|
It reduces your loan-to-value ratio, potentially giving you access to better mortgage rates in the future. |
You miss out on potentially higher returns from investments, savings, or your pension. |
|
You can lower your monthly repayments, giving you more disposable income each month. |
You might have to rely on expensive personal loans later if you run out of cash. |